
Cyprus Immigration’s Refusal to Accept Revolut Banking: An Unnecessary Obstacle for Residents
Cyprus promotes itself as an international business hub, welcoming foreign professionals, entrepreneurs, investors and families seeking a new life on the island. Yet, when it comes to immigration and personal banking, applicants can face a frustrating contradiction: difficulties using Revolut as their primary personal bank account.
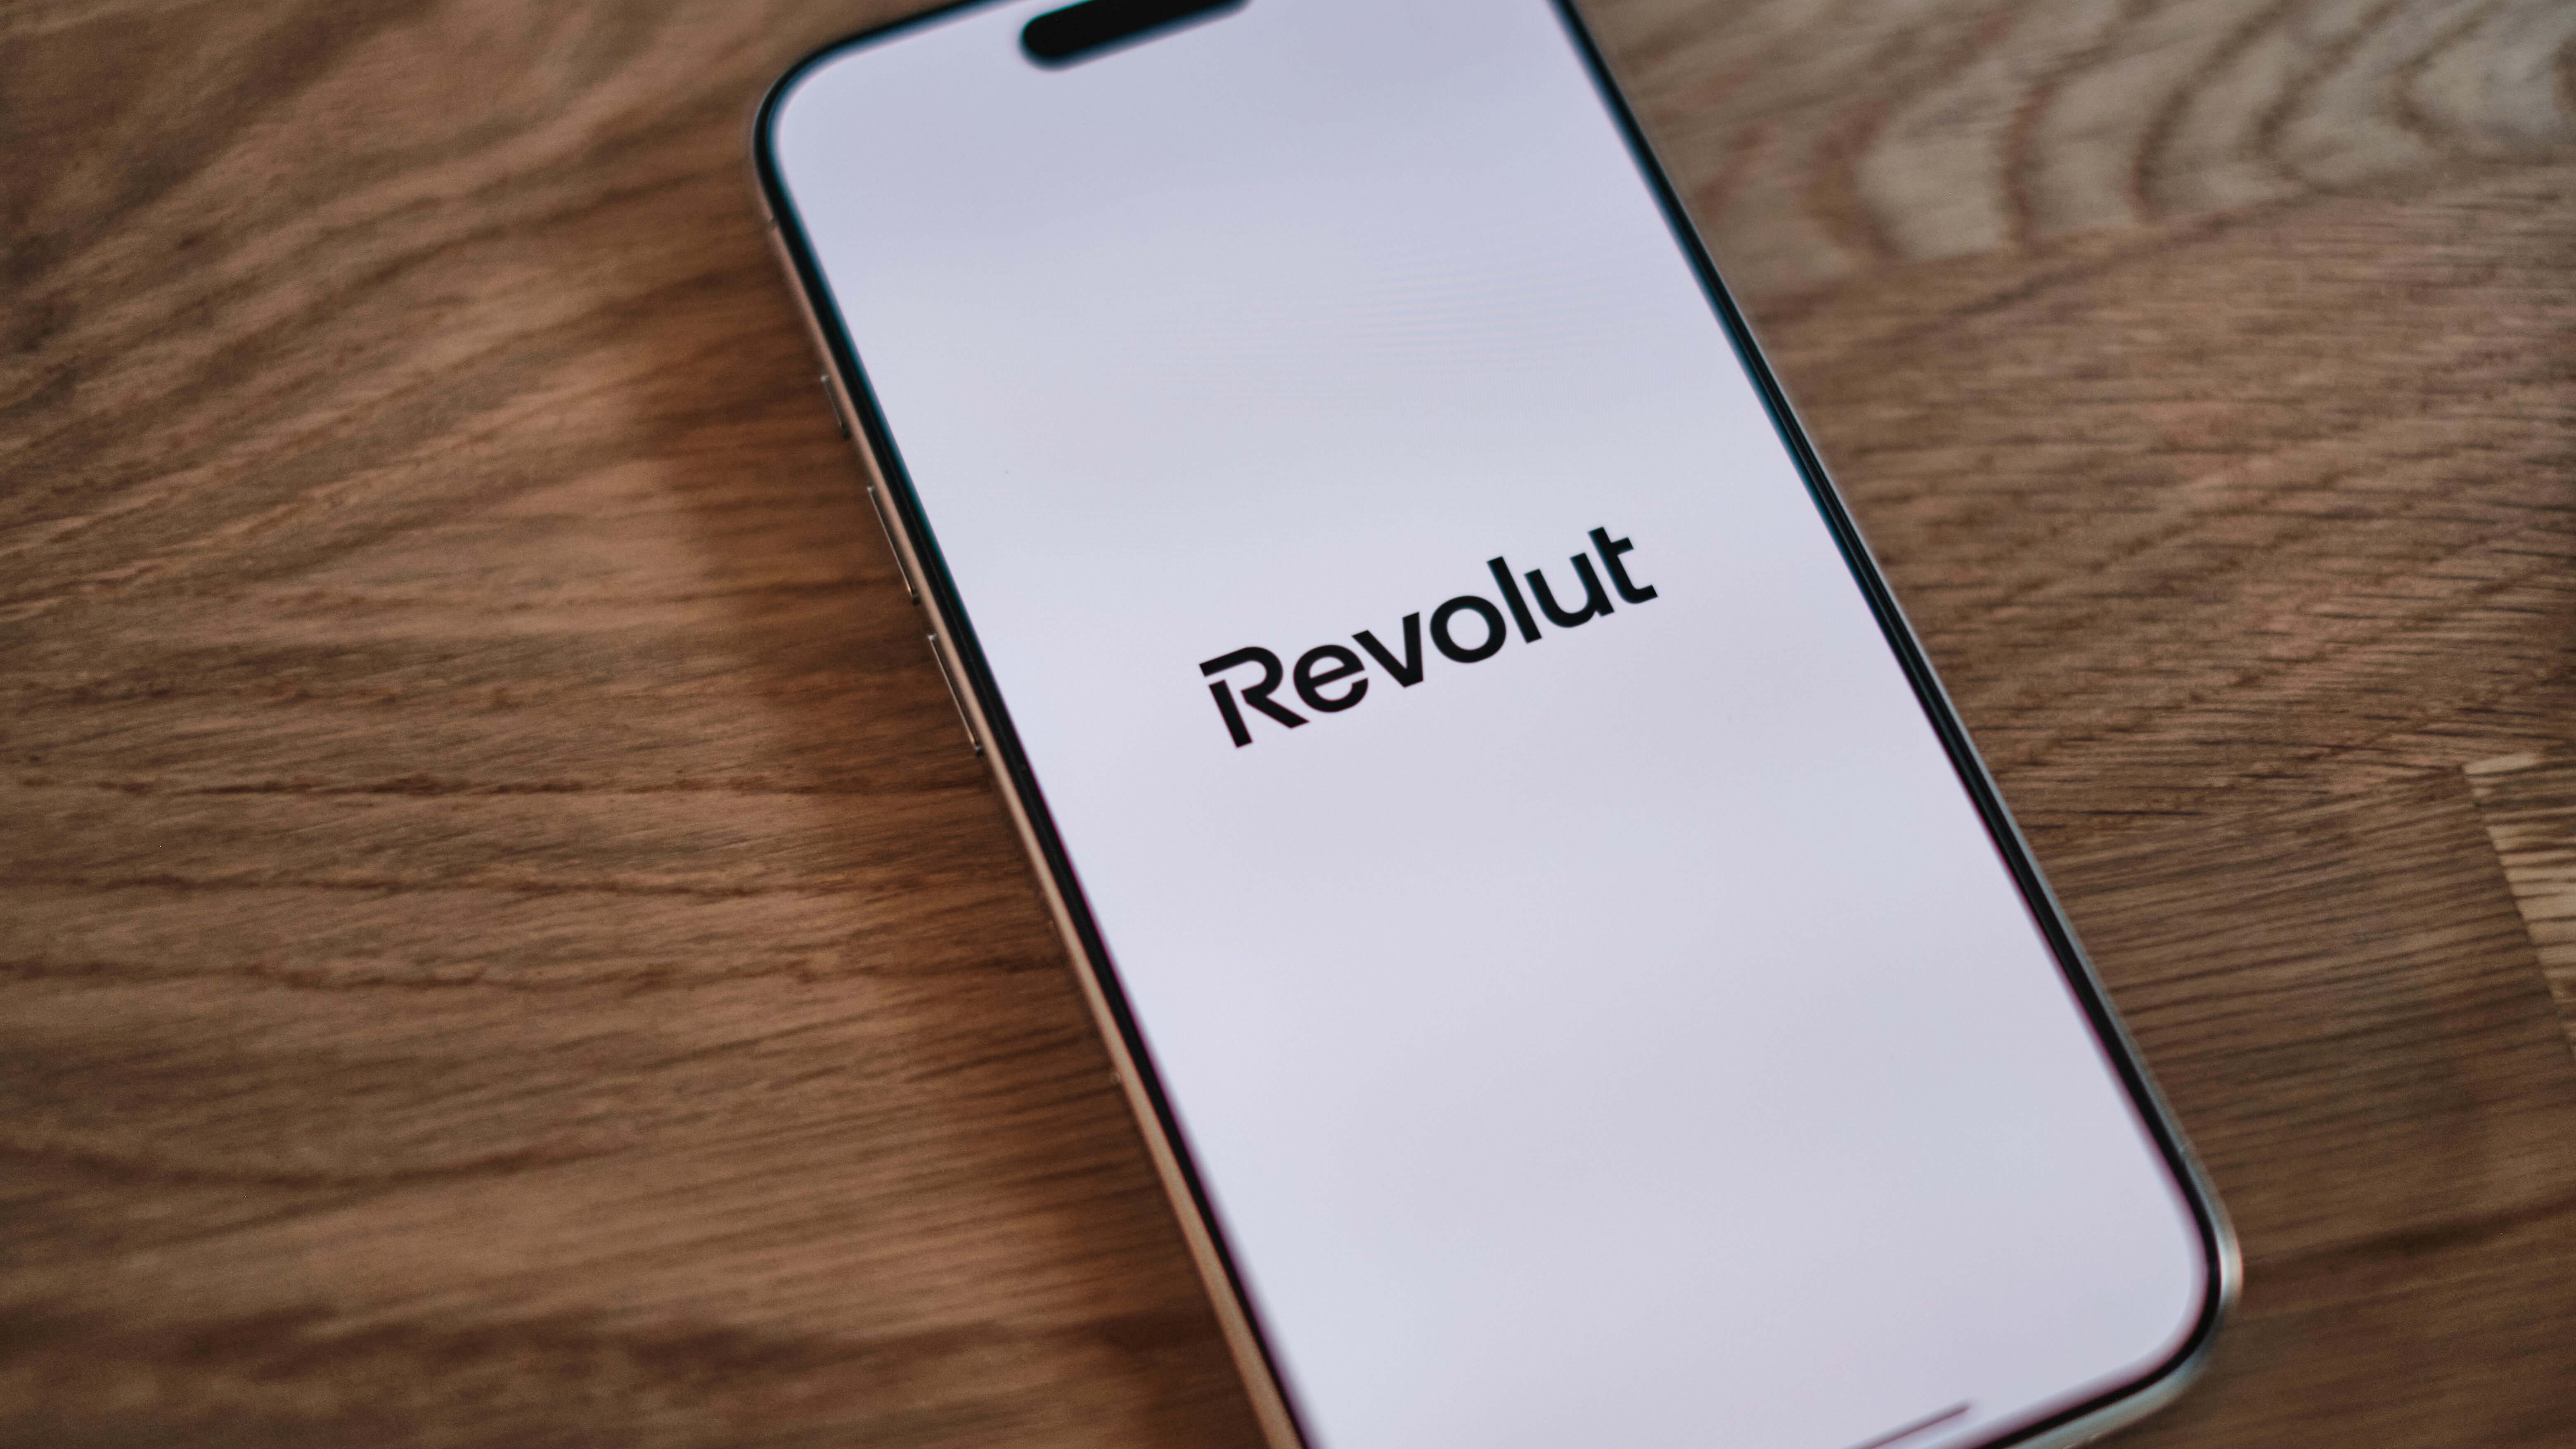
For many residents, Revolut is not simply an application for online purchases. It is their main financial account, used to receive money, manage daily expenses, transfer funds internationally and exchange currencies. Despite its popularity and convenience, applicants dealing with Cyprus immigration authorities can encounter problems when submitting Revolut statements as part of their residence applications. Some are told they need to open a traditional Cypriot bank account, even when they already have documented savings, regular income and an established banking relationship.
This creates additional expenses, unnecessary administrative work and potential delays. If an applicant can demonstrate their financial circumstances through legitimate, verifiable documentation, why should their choice of banking provider become an obstacle?
Cyprus needs a clearer, more consistent approach that recognises modern banking services while maintaining appropriate financial verification standards.
Why Are Applicants Being Asked to Open Another Bank Account?
Immigration authorities have legitimate reasons to request financial documentation. Depending on the residence permit, applicants may need to demonstrate sufficient funds, provide bank statements or prove regular income.
The problem is not the requirement to provide evidence. It is how that evidence is assessed.
When an applicant submits Revolut statements, the relevant questions should concern authenticity, account ownership, available funds, transaction history and whether the documents satisfy the applicable immigration requirements.
Instead, some applicants encounter difficulties because their existing banking arrangement is not considered acceptable for the purpose at hand. They may be required to establish another banking relationship, even when their current account already provides the financial information needed to assess their application.
Opening another account is not always straightforward. Banks may request additional documents, arrange appointments, conduct compliance checks and take time to approve applications. Applicants can find themselves waiting for a bank account simply to provide documentation for an immigration process that is already subject to deadlines and administrative requirements.
A modern immigration system should assess financial evidence according to clear criteria rather than automatically favouring traditional banking institutions.
Revolut’s Status in Cyprus: An Important Distinction
Revolut operates through different legal entities, and it is important to distinguish its banking services from its other financial activities.
The Cyprus entity identified in the information relevant to this discussion is Revolut Digital Assets Europe Ltd (RDAEL), registered with the Cyprus Registrar of Companies under number HE430310, with VAT number CY10430310Q and a registered address in Limassol. This entity is associated with crypto-asset services and is licensed as a Crypto-Asset Service Provider by the Cyprus Securities and Exchange Commission (CySEC).
However, a company registration and a licence for crypto-asset services are not the same as authorisation to provide banking services or accept deposits. RDAEL’s registration alone does not establish that it is the entity holding a particular customer’s Revolut bank deposits.
The relevant banking entity and its authorisation must be identified when assessing the regulatory status of an applicant’s account.
This distinction matters, but it does not eliminate the underlying issue. Where an applicant holds an account with an appropriately authorised banking institution and can provide official, verifiable documentation, the authorities should clearly explain whether those documents satisfy the applicable immigration requirements.
Regulatory status and immigration acceptance are two separate questions. A regulated financial service is not automatically acceptable for every immigration application. Equally, an alternative banking service should not be dismissed without clear guidance explaining the applicable requirements.
Applicants should not have to navigate complex corporate registrations, banking licences and financial regulations just to determine which statements they can submit.
Why So Many People Prefer Revolut
Revolut has become popular because it offers a convenient way to manage money, particularly for people who live, work or maintain financial commitments across different countries.
A more user-friendly experience
Customers can check their balances, review transactions, manage cards and retrieve account information through a single application. They can access financial records without visiting a branch or waiting for an appointment.
For foreign residents, this convenience is especially valuable. They may need to provide statements for immigration applications, demonstrate available funds or document incoming payments. Having these records readily accessible makes everyday financial management easier.
International money transfers
Many foreign residents receive income from overseas, support family members abroad or transfer funds between accounts in different countries.
Revolut offers international payment facilities that can make these transactions more convenient, depending on the destination, currency, account plan and applicable limits.
Traditional bank transfers may involve additional charges, intermediary fees, less favorable exchange rates or processing delays. These costs can be frustrating when customers are simply moving their own money.
Currency exchange when needed
Another major advantage is the ability to exchange currencies directly through the application.
Residents may receive income in one currency while paying expenses in euros. Others may maintain financial commitments in pounds sterling, US dollars or their home country’s currency.
Revolut allows eligible customers to exchange supported currencies conveniently, subject to the applicable rates, limits, plan conditions and fees. This can be particularly useful for people who regularly manage money internationally.
Better visibility over spending
Transaction notifications, spending categorization and budgeting tools also help customers monitor their finances. These features can be useful when relocating to Cyprus, where residents must manage rent, deposits, utilities, insurance and other expenses.
Traditional banks also provide digital services, and Revolut’s features and pricing vary by plan. Nevertheless, its convenience and international functionality explain why many people choose it as their primary account.
Customers should not have to abandon a banking arrangement that works for them without a clear and proportionate reason.
Traditional Cypriot Banks: Fees and Accessibility Concerns
Traditional banks play an important role in Cyprus, offering personal banking, local payment services, loans and other financial products. The problem arises when foreign residents feel they have little choice but to open an account, even when they already have a suitable alternative.
Opening a local account can involve extensive documentation, including identification, proof of address, employment details and source-of-funds evidence. These checks can be necessary, but the process becomes frustrating when requirements are unclear, appointments are difficult to obtain or applicants repeatedly have to provide additional documents.
Fees are another concern.
Depending on the institution and account type, customers may face monthly maintenance charges, card fees, transfer fees and other costs. Some fees may depend on account conditions, balances or activity, making it important to understand the applicable terms.
Not every Cypriot bank charges high fees, and some offer personal accounts with low or no maintenance charges. Nevertheless, customers should not be pushed towards an expensive banking arrangement without being given a clear explanation of the available alternatives.
The concern becomes particularly serious when an applicant believes that opening a local account is essential to completing an immigration application.
If a standard personal account is suitable for their circumstances, why should they have to consider a costly international banking product without first being told what other options exist?
The IBU Account Problem: Paying €45–€50 a Month
One of the most concerning issues reported by some foreign applicants is the difficulty of obtaining an ordinary personal account with a traditional Cypriot bank.
Instead, some applicants say they are directed towards an IBU account or another international banking arrangement. The terminology, eligibility requirements and product conditions can vary between institutions, so customers should always request the bank’s official account terms.
The reported concern is that people seeking a straightforward personal account for everyday banking and immigration purposes can be offered products with substantial recurring charges.
In some cases, applicants report being quoted approximately €45–€50 per month to maintain an account.
That amounts to €540–€600 annually.
For someone already paying rent, utilities, insurance, transportation costs and immigration-related expenses, this is a significant additional burden. The cost is even more frustrating when the account is being opened primarily because the applicant has been told that their existing banking documentation is not acceptable.
Imagine moving to Cyprus with your family, having sufficient savings and maintaining a functioning Revolut account. You are then told that you need a local bank account. When you approach a bank, the option presented to you costs hundreds of euros every year.
You may end up paying for two banking relationships, not because you genuinely need both, but because you are trying to satisfy an administrative requirement.
This is precisely why applicants need clear information before accepting an account.
If a standard personal account is available, customers should be told how to apply. If it is unavailable, they should receive a clear explanation of the eligibility criteria and the alternatives.
Foreign residents may be unfamiliar with the local banking system and may assume that the first product offered to them is their only option. When their immigration status feels dependent on obtaining an account, they may be reluctant to challenge the recommendation or question the fees.
Banks must comply with their legal and regulatory obligations, but customers should still be able to make informed decisions about the products they are offered.
Do Foreign Residents Have the Right to a Personal Account?
Foreign residents should receive fair consideration for personal banking services, but residence in Cyprus does not automatically guarantee an unconditional right to open an account with any bank.
Banks must comply with anti-money-laundering requirements, identity checks, sanctions obligations and other applicable rules. Eligibility may depend on residence status, tax residency, income, source of funds and the institution’s lawful policies.
However, applicants should not assume that an expensive international banking product is their only option.
Cyprus operates within the EU framework on access to basic payment accounts, including Directive 2014/92/EU. Eligible consumers who legally reside in the EU may have rights to access basic payment accounts, subject to the applicable conditions and exceptions.
A basic payment account is not necessarily equivalent to every account required for a particular immigration procedure, and it does not automatically guarantee acceptance of a residence application. Nevertheless, it is an important option to investigate.
Applicants should ask banks:
- Is this a personal account or an international banking product?
- Can I apply for a standard personal account instead?
- What are the monthly fees, minimum balance requirements and transaction charges?
- Can these fees change depending on my balance or account activity?
- If my application is rejected, can I receive the reasons in writing?
- Am I eligible for a basic payment account under the applicable rules?
These are reasonable questions. Customers should understand what they are paying for before committing to a banking arrangement.
The Consequences: Delays, Expenses and Unnecessary Stress
The Revolut issue is not just about banking preferences. It can affect the wider immigration process.
Applicants may need to arrange bank appointments, prepare additional documents, wait for compliance approval and obtain account statements before proceeding with their applications. If the first account offered is unsuitable or too expensive, they may need to approach another institution and start again.
For families, this creates additional uncertainty while they are managing accommodation, school expenses and residence documentation. Employees may face complications coordinating immigration and employment requirements, while entrepreneurs lose valuable time dealing with administrative obstacles.
Not every application involving Revolut will be delayed, and not every applicant will be directed towards an IBU account. Requirements vary according to the application and individual circumstances.
However, repeated difficulties should prompt the authorities to examine whether their procedures are sufficiently clear and proportionate.
If the purpose is to verify that an applicant has sufficient funds, the process should focus on reliable financial evidence. If a particular account type is legally required, that requirement should be clearly communicated.
Applicants should not be left guessing what is acceptable or spending unnecessary money simply to resolve uncertainty.
What Should Cyprus Immigration Authorities Do?
The authorities should establish clear, publicly accessible guidance explaining whether statements from regulated digital banks can be accepted for each relevant residence category.
The guidance should identify the required documents, the criteria used to verify account ownership and the circumstances in which additional evidence may be requested.
Where an applicant’s Revolut documentation is rejected, they should be able to request a written explanation. Was the problem the account’s legal status, missing documentation, insufficient financial evidence or a specific rule applicable to that residence category?
These are different issues that require different solutions.
Authorities should assess documents against clear criteria rather than relying on assumptions about a bank’s brand or digital interface. This does not mean every digital account must automatically qualify. It means that requirements should be transparent and consistently applied.
Better communication between immigration authorities, regulated financial institutions and professionals assisting applicants could also reduce unnecessary submissions and delays.
The objective should be straightforward: maintain proper verification standards without creating avoidable obstacles for people who are trying to comply with the rules.
What Applicants Can Do Right Now
Until the requirements are clarified, applicants should take practical steps to protect their interests.
First, ask for clarification. If you are told that Revolut cannot be accepted, request the specific reason and ask which requirement applies to your residence category.
Second, prepare official documentation. Depending on the application, this may include account statements, account ownership confirmation, transaction records and documentation identifying the entity providing the banking service.
Third, question expensive banking offers. If a bank recommends an IBU or international account, request the full terms and conditions, all applicable fees and an explanation of why that product is suitable for your circumstances.
Fourth, explore alternatives. Different banks have different account types and eligibility requirements. An unsuitable offer from one institution does not automatically mean that every other bank will offer the same terms.
Fifth, keep written records. Save emails, fee quotations, appointment confirmations and explanations from the bank or immigration authority. These records can help you obtain further clarification or professional assistance.
Most importantly, do not assume that the first account offered to you is automatically your only option. Understand the requirements before committing to an account that could cost hundreds of euros every year.
How Rideo Group Helps Applicants Navigate the System
At Rideo Group, we understand that navigating Cyprus immigration procedures can be complicated enough without additional obstacles arising from banking arrangements.
We have been guiding clients through the Cypriot banking system and assisting them in identifying suitable banking options for their immigration purposes.
For many applicants, the challenge is not simply opening an account. It is understanding which account is appropriate, what documentation is needed, what fees may apply and how the banking arrangements fit into the wider residence application.
We help clients understand the process, prepare the necessary documentation and navigate available options according to their individual circumstances.
Where clients encounter difficulties with Revolut documentation or are offered banking products that appear unsuitable for their needs, we help them understand the next steps and identify the questions they should raise with the relevant bank or authority.
Every case is different. Neither opening an account nor acceptance of particular statements can be guaranteed, as banks retain their compliance obligations and immigration decisions remain with the competent authorities.
Nevertheless, applicants deserve practical guidance and clear information rather than being left to navigate the system alone.
We will continue assisting our clients in finding appropriate banking arrangements for their circumstances while advocating for clearer, more consistent procedures.
Final Thoughts: Cyprus Needs to Catch Up With Modern Banking
The frustration surrounding Revolut and Cyprus immigration reflects a wider problem: applicants can end up spending additional time and money satisfying administrative expectations that are not always clearly explained.
Revolut offers convenient account management, international transfers, currency exchange and accessible financial records. These features make it an attractive option for many foreign residents.
Traditional banks remain important, but that does not justify creating unnecessary obstacles for applicants who already have legitimate, documented financial arrangements.
The reported practice of directing some applicants towards international banking products costing €45–€50 per month is particularly concerning when they are simply seeking a personal account for everyday use and immigration documentation.
Applicants should ask questions, compare options and request written explanations rather than automatically accepting expensive offers. Banks should clearly explain their account products, eligibility requirements and fees. Immigration authorities should publish transparent guidance on the acceptance of digital bank statements.
At Rideo Group, we hope that Cyprus will establish a clear framework under which qualifying Revolut banking documentation can be accepted when it satisfies the applicable immigration requirements.
A person who can demonstrate their financial circumstances through legitimate, verifiable evidence should not have to navigate unnecessary administrative obstacles simply because they prefer digital banking.
Cyprus can do better. Its residents and applicants deserve an immigration and banking system that reflects modern financial realities rather than making compliance more complicated and expensive than necessary.
Disclaimer:
The information in this article reflects the legal framework and practical realities as of 2026. Laws and procedures may evolve. For up-to-date advice tailored to your case, we recommend booking a consultation with Rideo Group’s expert team.